

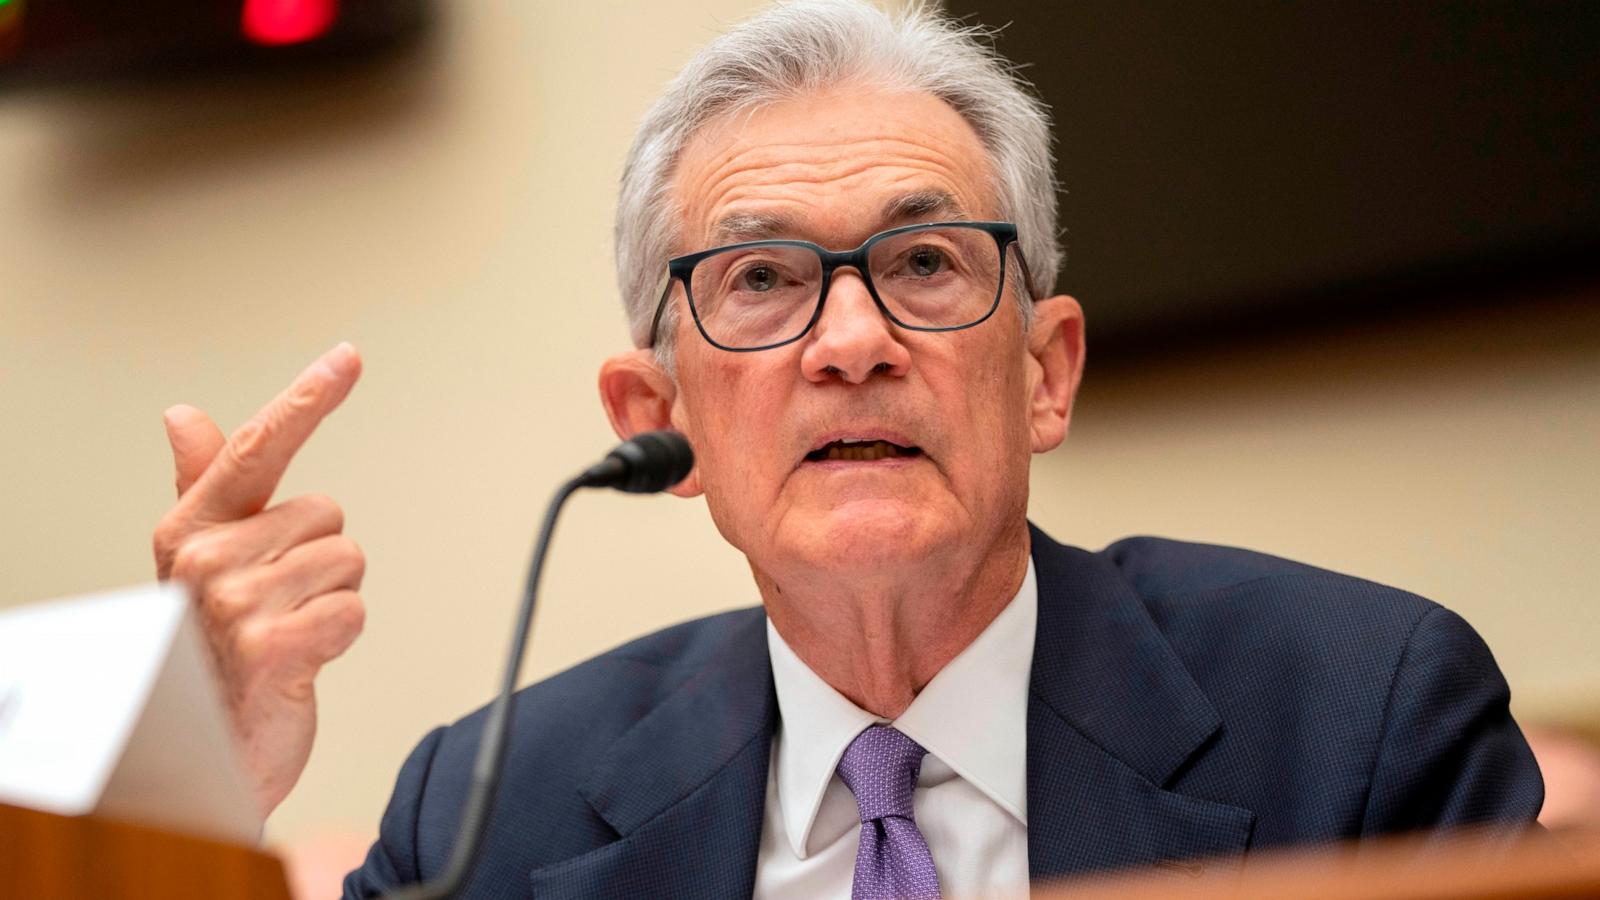

A prominent official at the central financial institution has expressed openness to cutting interest rates if future economic reports persistently show a decline in the job market. Although the prevailing monetary strategy remains prudent because of ongoing inflation worries, recent signs imply that the labor sector’s strength might be diminishing—a crucial aspect that could impact upcoming policy choices.
During a recent economic forum, the bank representative highlighted the significance of closely observing labor patterns, mentioning that although job growth continues to be positive, the speed seems to be slowing down. Unemployment rates, despite staying relatively low, have experienced slight rises in certain areas, and salary increases are starting to slow. These patterns might indicate a more extensive change in economic circumstances, suggesting a possible alteration in monetary policy.
Interest rates have been kept high to tackle inflation, but they might be lowered if the central bank assesses that economic pressures are moving from overheating to stagnation. The central bank aims for both price stability and full employment, so indications of stress in the employment sector might lead to a relaxation of financial conditions.
Over the past year, the central bank has maintained a firm stance on curbing inflation, using rate hikes as a primary tool to cool consumer spending and reduce price pressures. However, as inflation shows signs of moderation and growth projections are revised downward, the focus is gradually returning to employment health. Analysts have been watching for any pivot in rhetoric that might suggest a softer policy outlook, and recent comments from central bank leadership may reflect the early stages of such a shift.
Yet, the possibility of any rate decreases in the future depends on additional information. The central bank is improbable to undertake major actions based on temporary changes, opting instead to depend on enduring patterns in a range of economic signals. These encompass not just job statistics, but also corporate investment, consumer sentiment, and inflation forecasts. Any move to reduce interest rates would be considered within the bigger picture of maintaining prolonged economic steadiness, rather than responding to singular data occurrences.
Certain economists suggest that the recent slowdown in the job market might be a normal adjustment following the increase in hiring after the pandemic, instead of an indication of more serious economic issues. Alternatively, some caution that a decrease in the demand for workers, if not tackled, could result in increased unemployment rates and decreased consumer spending—elements that could exacerbate any recession.
The strategy employed by the central bank is often characterized by being adaptable and guided by data. Authorities have continuously expressed their plan to be attentive to economic changes instead of adhering strictly to a set course. This adaptability permits decision-makers to consider various scenarios and prevent excessive measures that could either hinder economic expansion or let inflation rise again.
Market participants are paying close attention to upcoming labor reports, as well as any revisions to previous data, which can significantly influence sentiment and expectations. Financial markets tend to respond quickly to changes in interest rate policy, affecting everything from mortgage rates and consumer loans to business financing and foreign exchange rates. A potential rate cut, therefore, could have wide-reaching implications across the economy.
The implications of a shift in monetary policy extend beyond the domestic economy. International investors, trade partners, and foreign central banks monitor the signals from major financial institutions closely, as rate changes can influence global capital flows and currency valuations. If the central bank moves toward easing while others maintain tighter policies, exchange rate volatility and trade imbalances could become part of the broader discussion.
Consumer groups and labor advocates have welcomed the possibility of a rate reduction, arguing that high interest rates disproportionately affect working-class households and small businesses. They highlight that credit conditions have become increasingly restrictive, limiting access to funding for homebuyers, entrepreneurs, and everyday consumers. A reduction in borrowing costs, they say, could offer much-needed relief without necessarily undermining the progress made in controlling inflation.
Conversely, several financial analysts warn that a rapid reduction of rates might undo the progress achieved in combating inflation, especially if there is a resurgence in wage increases or ongoing supply-side challenges. It is crucial for the central bank to find a careful equilibrium—boosting employment without reviving the same inflationary forces it has diligently sought to control.
In the coming months, a lot will hinge on the way the data changes. If job figures keep declining, the case for reducing rates might gain momentum. On the other hand, if inflation stays persistent or international economic dangers grow, the central bank might decide to maintain its current path.
For now, the message from central bank leadership is one of measured observation and readiness. The acknowledgment that rates could be lowered if job market conditions worsen provides both reassurance to markets and a signal that policymakers are attuned to the challenges facing workers and businesses alike. This pragmatic, responsive stance may help maintain stability as the economy continues to navigate a period of uncertainty and transition.

